Weekly outlook, Week of 9th–13th November 2026
Oil is back at the bottom of value, and diesel isn't selling
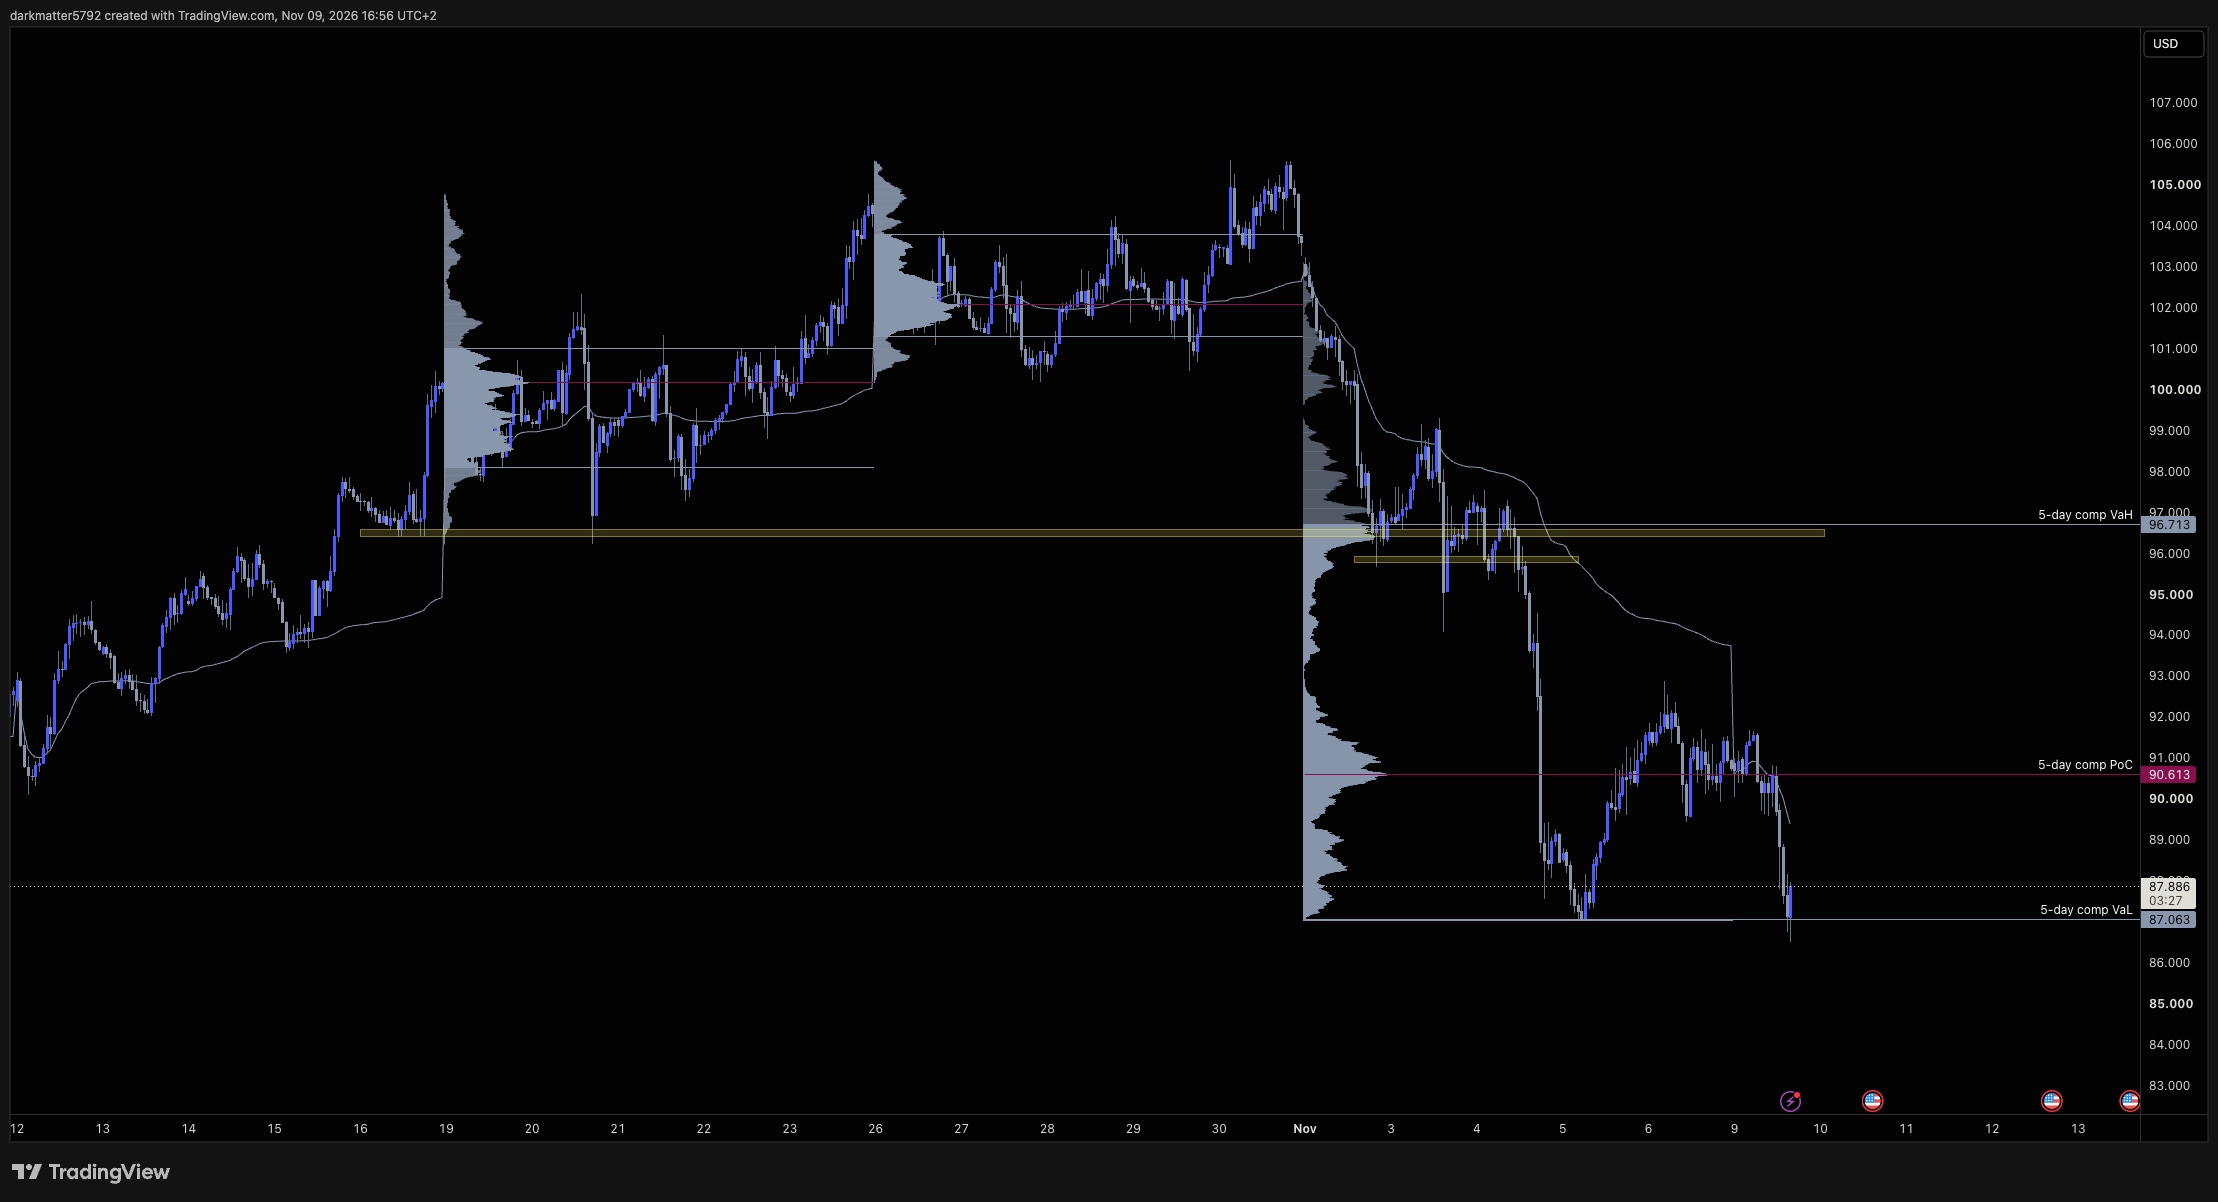
Biggest weekly drop since 2022, and the war premium is mostly gone. What's left is a backwardated curve, a diesel crack that held while flat price lost 13%, and funds that already sold. Monday's dip on an unconfirmed Hormuz report broke last week's $87.1 VaL and came straight back. Long above Monday's low, targets the $90.6 PoC, then $92.8.
- Crude oil
-
WTI crude USOUSD
Bullish above $86.4
Mon low$86.4VaL$87.1PoC$90.6Thu high$92.8Breakout$96.2VaH$96.7$87.9
Buy zone Sell zone Price at 14:56 GMT Monday. VaH, PoC, VaL: last week's 5-day composite (2nd–6th November). Mon low: Monday's low. Thu high: last week's rebound high. Breakout: VaH, week of 12th October.
Cracks, spreads, flows
The premium came out. The barrel didn't. Front-month crude had its biggest weekly drop since 2022: Brent about 16%, WTI more than 13%. Diplomacy did it, plus Gulf exports coming back with tankers still getting hit in Hormuz. There is still no agreement. Iran wants the US blockade lifted, sanctions eased and frozen assets released before it fully reopens the strait. That's a long list. The market priced the deal anyway.
Monday added another leg on an unconfirmed report that Iran had dropped its Hormuz toll demand. A Qatari official called it false. US and Gulf officials aren't expecting a breakthrough this week. Price broke last week's value on a headline that's already been denied.
The curve
Flatter, still backwardated. On Friday's settles against the Friday before, WTI Dec/Jan lost about a third and Jan/Mar about 30%. Monday took Dec/Jan another 13% narrower. Brent Jan/Feb lost about 30% on the week and Jan/Mar about 30%. That's the bear case, and it's real. But both curves are still in backwardation after a 13–16% flat price wipe-out. Prompt barrels still cost more than deferred ones. Nobody is paying to store crude yet.
The arb closed. The Brent–WTI Jan futures spread lost more than a fifth on the week and is narrower again Monday. Dated Brent over WTI Cushing was $7.4 on Tuesday 3rd November on EIA spot, from $19.7 a week earlier. Brent carried the war premium and gave most of it back. WTI fell less. US crude exports were already down 1.18M b/d to 3.68M b/d in the week to 30th October, and Cushing built to 27.3M bbl, 9.2% over the 5-year average. That's the WTI spread's problem, and it's why Dec/Jan is the leg to watch.
Refinery margins
Diesel held. Flat price fell 13% on the week. The futures diesel crack finished about 1% lower. Heating oil Dec/Jan finished about 15% wider. The market sold crude and kept paying for distillate. On EIA spot, the Gulf Coast diesel crack was $90.4 on 3rd November, New York Harbor $102.9. Distillate stocks are 99.3M bbl, 13.3% under the 5-year average, going into winter. That's the floor under crude runs, and under crude.
Gasoline is the soft leg. Futures gasoline crack about 10% lower on the week. Gulf Coast gasoline crack $22.3 on EIA spot, 3-2-1 $45.0 from $50.2 the week before. Asian gasoline margins are at multi-month lows. The barrel is a diesel story, top to bottom.
Funds
Managed money already sold. Net long 21,728 WTI contracts on Tuesday 3rd November, down 9,400. Longs cut 10,051, shorts barely moved. That's liquidation, not new selling. The net sits at the 21st percentile of its 3-year range, and it's measured before Wednesday's 8% flush. Friday's report will show less. There isn't much length left to puke. (Charts.)
The read: the war premium is out and the physical market is softer than it was in October. But the curve is still backwardated, the diesel crack didn't move, and funds are light. Monday's break of last week's value came on a denied headline. Flat price has overshot the barrel. Long the failed break, out if the curve flips.
The auction
Last week's 5-day composite: VaH $96.7, PoC $90.6, VaL $87.1. It's a trend-week profile. The top half is thin: Monday and Tuesday's trade around $96–98, then Wednesday's vertical break through it. The volume is at the bottom: Thursday and Friday built value around the $90.6 PoC after the $87.1 Thursday Asia low. The rebound topped at $92.8 and Friday held $89.5–91.6.
Monday gapped under Friday's range, sold through the $87.1 VaL and printed $86.4. No follow-through. At 14:56 GMT WTI is $87.9, back inside last week's value. That's a look below and fail at the edge of value, on the second test of $87.1 in three sessions.
Back inside value, the auction rotates to the PoC: $90.6. Above that, $92.8 is the top of the rebound and the start of the thin volume. Nothing above $92.8 until the $96.2–96.7 shelf: the old breakout from the week of 12th October and last week's VaH. Under $86.4, value is rejected from below and last week's VaL becomes resistance.
The week
- Talks drag. The base case. The denied Hormuz report fades, Monday's low holds, and price rotates back to the $90.6 PoC. Through $92.8 the thin volume runs to $96.2.
- Deal. A signed framework with a reopening date. Price leaves value under $86.4 and the long is stopped. Watch Brent–WTI: Brent has more premium left to lose, so WTI falls less.
- Talks break. Iran's preconditions stay unmet and Gulf tanker attacks continue. The curve rebuilds first, then flat price. $96.2–96.7 comes quickly from $92.8.
Watch Dec/Jan. Narrowing while price holds $87.1 is a warning. Widening with price back over $90.6 confirms the long.
What matters in Thursday's EIA
- Cushing. A draw back under 27M bbl supports Dec/Jan into expiry. Another build is the bear case for the WTI curve.
- Exports. With the arb at $7, under 3.5M b/d keeps barrels at home. Watch Gulf Coast stocks.
- Distillates. A fourth straight draw keeps the diesel crack over $90 and the bull case intact.
- Runs. Utilisation holding over 92% means refiners are still buying crude for diesel.
WTI levels and setups
Long. Buy $87.0–87.8, back above last week's VaL. Stop $85.9. Targets $90.6, then $92.8.
Buy setup failed break of last week's value
- Buy zone
- $87.0 – $87.8 Back above last week's $87.1 VaL
- Stop-loss
- $85.9 Under Monday's $86.4 low
- Targets
- $90.6 / $92.8 Last week's 5-day composite PoC, then last week's rebound high
Invalidation: Daily close under $86.4: Monday's low gone, last week's value rejected from below, no long. WTI Dec/Jan or Brent Jan/Feb flipping to contango kills the bullish bias for the week, whatever price does.
| Level | What it is | Role this week |
|---|---|---|
| $96.7 | Last week's 5-day composite VaH | Top of value |
| $96.2 | VaH, week of 12th October | Breakout shelf; resistance |
| $92.8 | Last week's rebound high | Second target; thin volume above |
| $90.6 | Last week's 5-day composite PoC | First target |
| $87.9 | Price | Back inside value |
| $87.1 | Last week's 5-day composite VaL | Weekly pivot; buy zone |
| $86.4 | Monday's low | Bias flips under |
| $85.9 | Under Monday's low | Stop |
What would change the view
Daily close under $86.4: last week's value rejected, no long. In the barrel: WTI Dec/Jan or Brent Jan/Feb in contango, or the Gulf Coast diesel crack under $80. In the news: a signed US–Iran framework with a Hormuz reopening date. Any of these, and this outlook gets updated.
The week ahead (London time)
- Monday: Qatar's prime minister at the White House.
- Tuesday 17:00: EIA Short-Term Energy Outlook (November)
- Wednesday: Veterans Day. US federal holiday; the API and EIA stock reports each move back a day.
- Thursday 13:30: US weekly jobless claims
- Thursday: EIA Weekly Petroleum Status Report, week to 6th November
- Friday 18:00: Baker Hughes US rig count
- Friday 20:30: CFTC Commitments of Traders (positions to Tuesday 10th November)
December WTI expires on Friday 20th November, next week. A Cushing build into expiry is the risk to Dec/Jan.
Cracks and Dated Brent–WTI are calculated from EIA daily spot prices against WTI Cushing (latest published: Tuesday 3rd November). Timespreads and futures cracks are described from futures settlements, not quoted. Prices are taken from a CFD feed (USOUSD) and can differ from futures prices and from your broker's quotes.