Daily note, Tuesday 10th November 2026
Hot CPI put in oil's low, and the curve didn't follow
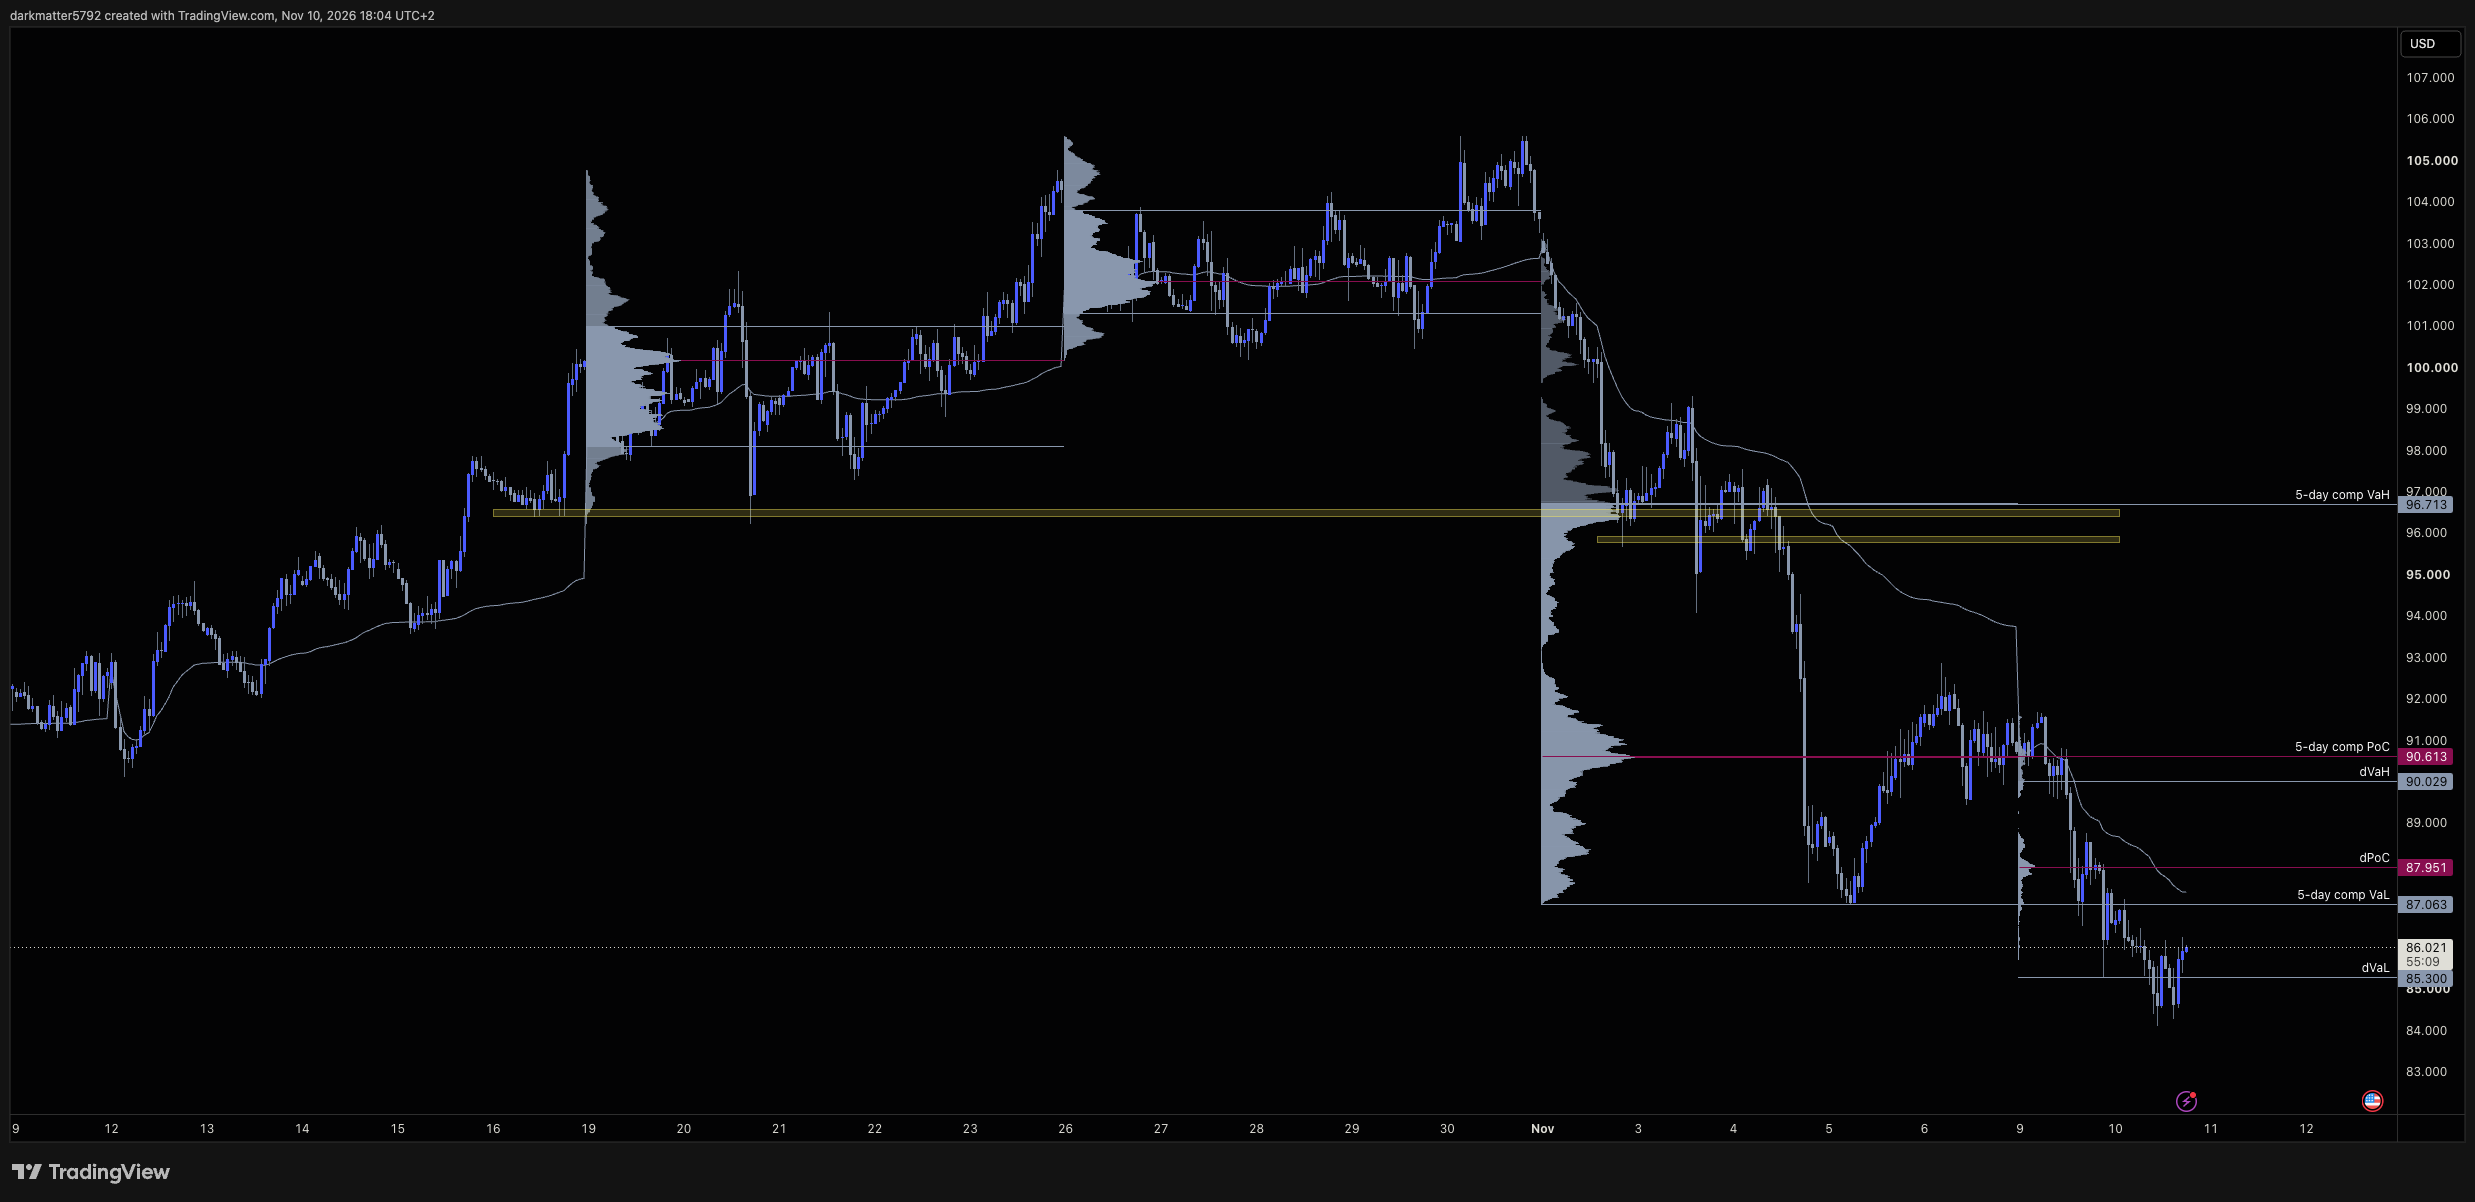
October CPI came in at 0.4% against 0.2% expected, core 0.3% against 0.2%, and a 50bp Fed hike is now being talked about. WTI made the day's low on the print, $84.2, then took back $1.8 to $86.0. WTI timespreads finished the day a touch wider and Brent's held flat. Flat price fell, the curve didn't. Cracks are the weak spot: diesel and gasoline both about 5% lower. Price is back inside this week's developing value. Long the $85.3 retest to $87.1, then $88.0. Short a rejection at $87.1–87.4 back to $85.3.
Levels in this post are from a CFD feed (USOUSD). Since 16th November 2026 the site uses NYMEX WTI and ICE Brent futures, so these levels sit at a basis to futures.
- Crude oil
-
WTI crude USOUSD
Neutral, $85.3–87.1
CPI low$84.2dVaL$85.3VaL$87.1VWAP$87.4dPoC$88.0dVaH$90.0PoC$90.6$86.0
Buy zone Sell zone Price at 16:05 GMT. dVaH, dPoC, dVaL: this week's developing 5-day composite (from Monday 9th November). VaL, PoC: last week's 5-day composite (2nd–6th November). CPI low: Tuesday's low on the CPI print. VWAP: this week's, at 16:05 GMT Tuesday.
Cracks, spreads, flows
CPI was hot. October CPI rose 0.4% on the month against 0.2% expected (FactSet consensus). Core rose 0.3% against 0.2%. BLS published no year-on-year figure, because of last year's shutdown gap. Pantheon's Samuel Tombs says it puts a 50bp hike on the table. It's the last CPI before the Fed's December meeting. Higher rates and a firmer dollar are a demand problem for crude, and the market sold it at once.
The print made the low, then the market bought it. WTI was already under Monday's $85.3 low after the Asian session, on Trump saying military action against Iran isn't needed "at this point". At 13:30 GMT it dropped another $0.9 in fifteen minutes to $84.2, the low of the day. It took back the whole move inside ninety minutes. At 16:05 GMT it's $86.0, $1.8 off the low.
The curve didn't follow. WTI futures were about 1.3% lower on Monday's settle at 16:00 GMT and Brent about 1.9%. The spreads didn't move with them. WTI Dec/Jan finished about 3% wider and Jan/Mar about 4% wider. Brent Jan/Feb is about 2% narrower and Jan/Mar is flat. After Monday's fifth off Brent's curve, that's a hold. Flat price fell on rates and headlines. The prompt barrel didn't get any looser today.
Brent keeps giving back the premium. The Brent–WTI Jan futures spread lost about 8% on the day, after losing a fifth on Monday. Brent carried the war premium and Brent is still where it's coming out. Attacks on shipping around Hormuz haven't stopped, but they haven't escalated either, and nothing new is being priced for them. Dated Brent was $7.4 over WTI Cushing on EIA spot on 3rd November. The arb is shut, and WTI barrels that can't get out end up in Cushing.
Cracks are the weak spot. The futures diesel crack is about 5% lower on Monday's settle and the gasoline crack about 4% lower. Heating oil Dec/Jan is about 7% narrower. Products fell harder than crude. On EIA spot for 3rd November: Gulf Coast diesel crack $90.4, 3-2-1 $45.0. Those margins still pay refiners to run hard. Distillate stocks are 99.3M bbl, 13.3% under the 5-year average. If the cracks keep sliding with crude, the floor under runs goes with them.
Cushing is still the test. Cushing is 27.3M bbl, 9.2% over the 5-year average. Exports were 3.68M b/d in the week to 30th October. Dec/Jan held through Monday's flush and today's CPI low. Thursday's EIA report is the next test. Another Cushing build puts Dec/Jan on Brent's path into December expiry on Friday 20th November. December options expire next week, with heavy open interest at the round strikes. Dealer hedging turns a $1 move into $2 around them.
EIA's November outlook is behind the tape. The Short-Term Energy Outlook came out at 17:00 GMT, with the forecast closed on 5th November. EIA has Brent around $100 through November and December, under $90 in the second quarter of 2027 and $77 by the fourth. Middle East shut-ins were 2.5M b/d in October, from 10.9M b/d at the May peak, and stay flat for the rest of 2026. Global stocks fell 1.2M b/d in the third quarter, start building in the fourth and build 3.5M b/d in the first half of 2027. 2026 demand is down 2.0M b/d, mostly China and the Middle East, and comes back by 2.0M b/d in 2027. Iran's exports stay constrained through 2027. The direction matches the curve: stocks build from here. EIA puts the price path well above where the market already trades.
The read: The macro was bearish and the market sold it. The curve didn't sell with it, and price took back the whole CPI move. That's two days running that flat price broke a low on no barrel signal. The damage is in the cracks and in the Brent–WTI spread, not in the prompt WTI spread. Inside $85.3–87.1, play the edges.
The auction
This week's developing 5-day composite (from Monday 9th November): dVaH $90.0, dPoC $88.0, dVaL $85.3. The dVaL sits on Monday's post-settlement low. Last week's 5-day composite: VaH $96.7, PoC $90.6, VaL $87.1.
Tuesday opened under last week's value and sold through $85.3 in Europe. The CPI print took it to $84.2. There was no acceptance down there. Two pushes under $85.3 and both came straight back. Price is $86.0, back inside this week's developing value and under last week's.
That makes $85.3–87.1 the box. $85.3 is the developing dVaL and the reclaimed low. $87.1 is last week's VaL, with this week's VWAP at $87.4 just over it. Over $87.4, price is back in last week's value and the $88.0 dPoC is next, then the $90.0 dVaH. Under $85.3 on acceptance, the CPI low at $84.2 is the only level on this chart.
WTI levels and setups
Neutral, $85.3–87.1. Long the retest of $85.3: buy $85.3–85.7, stop $84.0, targets $87.1, then $88.0. Short a rejection of $87.1–87.4: hourly close back under $87.1, sell $86.9–87.2, stop $88.1, targets $85.3, then $84.2.
Buy setup retest of the reclaimed low
- Buy zone
- $85.3 – $85.7 Developing dVaL and Monday's low, retaken after CPI
- Stop-loss
- $84.0 Under the $84.2 CPI low
- Targets
- $87.1 / $88.0 Last week's 5-day composite VaL, then the developing dPoC
Sell setup only on rejection
- Trigger
- Test of $87.1–87.4, then an hourly close back below $87.1
- Sell zone
- $86.9 – $87.2 Under last week's VaL and this week's VWAP
- Stop-loss
- $88.1 Over the $88.0 developing dPoC
- Targets
- $85.3 / $84.2 Developing dVaL, then the CPI low
Invalidation: Hourly acceptance under $85.3 kills the long: the CPI reclaim has failed and $84.2 is the only level under it on this chart. Hourly acceptance over $87.4 kills the short: price is back in last week's value and over the VWAP, and $88.0 then $90.0 are next. WTI Dec/Jan narrowing while price falls makes the short a barrel trade, not just flat price.
| Level | What it is | Role today |
|---|---|---|
| $90.6 | Last week's 5-day composite PoC | Resistance |
| $90.0 | This week's developing dVaH | Resistance; top of developing value |
| $88.0 | This week's developing dPoC | Second long target; short stop over it |
| $87.4 | This week's VWAP | Top of the sell zone |
| $87.1 | Last week's 5-day composite VaL | First long target; short on rejection |
| $86.0 | Price | Inside developing value |
| $85.3 | Developing dVaL; Monday's low | Long on the retest; first short target |
| $84.2 | Tuesday's CPI low | Long stop under it; second short target |
The next three days (London time)
- Wednesday: Veterans Day. The API and EIA stock reports each move back a day.
- Thursday: EIA Weekly Petroleum Status Report, week to 6th November. Cushing and exports are the numbers.
- Friday 19:30: CFTC Commitments of Traders, to Tuesday 10th November. It catches last week's flush, Monday and the CPI low.
Cracks and Dated Brent–WTI are calculated from EIA daily spot prices against WTI Cushing (latest published: Tuesday 3rd November). Timespreads and futures cracks are described from futures prices against Monday's settlement, not quoted. Prices are taken from a CFD feed (USOUSD) and can differ from futures prices and from your broker's quotes.